Time:2026-10-06 Form:本站
As the global dental implant consumables market continues to evolve, a growing number of implant distributors are moving beyond the traditional brand agency model to establish direct manufacturing partnerships with production factories. In the past, distributors’ core work involved representing established brands to complete regional distribution, inventory management and end-clinic services. However, compounded by intensifying market competition, supply chain volatility, diversified demands from end dental clinics and constraints from brand agency terms, many distributors have realised that the growth room under the pure agency model is narrowing.
Direct manufacturing partnership is far more than simply sourcing goods from factories. It is a long-term partnership with in-depth collaboration, taking multiple forms including OEM manufacturing, private-label customisation, joint product iteration, technical synchronisation and coordination on compliance documentation. Through such partnerships, distributors can seize control of their supply chain, build differentiated product lines, optimise profit structures and better respond to the real clinical needs of dental clinics and dental laboratories.
Within the traditional distribution system, regional distributors rely on the reputation and established qualifications of major brands to run their businesses. This model was efficient and stable in the early stage of market growth, yet its drawbacks have gradually emerged as the industry develops.
Compressed profit margins across multi-tiered channels: Leading international implant brands maintain a complete pricing system. After multi-level distribution transfers, regional distributors are left with fixed gross profit margins. When regional market competition intensifies and clinics keep pushing down prices, distributors struggle to adjust product costs independently and face heavy profit pressure.
Restrictive agency agreements with limited operational flexibility: Most brand agency contracts set minimum annual procurement targets, regional price protection and sales restrictions on products. Failure to meet procurement quotas may result in revocation of agency qualifications. Product pricing, new product launches and inventory allocation must all follow unified arrangements from the brand owner, leaving distributors little room for independent adjustment.
Long technical feedback and product iteration cycles: Clinical issues reported by clinics are relayed from distributors to the R&D departments of brand headquarters through multiple handovers, resulting in lengthy lead times. Demands for interface updates, optimisation of accessory compatibility and upgrades for digital supporting products can hardly be implemented quickly. For niche categories such as multi-system compatible components, major brands often update at a pace lagging behind market demand.
Severe homogenisation of product lines: Multiple distributors in the same region represent the same brand with identical products. Competition is driven solely by price cuts, making it difficult to build differentiated barriers of their own, and customers can easily switch to competitors.
The transition from brand agency to direct manufacturing partnerships is not a short-term trend-chasing choice. It is an inevitable outcome driven by industry transparency, supply chain maturity and refined end-user demands, delivering value upgrades in four key dimensions.
Under the traditional agency model, brand premiums, markup by regional general agents and channel diversion costs stack up, creating rigid end-user pricing. Distributors can only earn fixed margins passively. Once the market enters a price competition phase, profits keep shrinking, even leading to high sales volume with no profit.
Direct manufacturing cooperation removes intermediate channel links entirely. Distributors gain access to original production costs and full pricing autonomy. They can either retain higher profit margins or offer flexible quotations in the end market, securing major clients with cost-performance advantages and expanding into lower-tier markets. Especially for high-frequency consumables such as healing abutments, impression copings, implant analogues and restoration screws, which have large sales volume and stable repeat orders, the cost advantage of direct supply keeps amplifying and becomes a core pillar for stable channel profitability.
The biggest pain point of brand agency is “lack of differentiation”. All distributors share the same products, identical parameters and packaging, making it extremely easy for customers to compare prices and triggering vicious price wars. In contrast, direct manufacturing partnerships grant distributors autonomy in product customisation and category layout.
Distributors can flexibly configure SKU portfolios based on mainstream local implant systems and end-clinic clinical habits, and targetedly supplement hard-to-source accessories of older versions and digitally compatible accessories as well as high-load restoration components. Meanwhile, private-label OEM customisation is available to create exclusive packaging, product logos and promotion systems, completely escaping homogenised competition and building independent customer recognition and brand barriers.
Ongoing iteration of implant brand interfaces, incompatibility between parameters of old and new versions, discontinuation of older accessories and delayed release of matching new components are common challenges faced by dental clinics worldwide. Under the traditional agency model, distributors cannot interfere with brand R&D schedules and can only passively wait for new product launches. It often happens that market demand surges while products are out of stock, or compatibility issues of older versions remain unsolved.
By establishing direct cooperation with qualified manufacturing factories, market feedback, clinical demands and product optimisation can be communicated bidirectionally and directly. Specialised implant component manufacturers represented by RE-TECH continuously track the iteration of major mainstream brand systems, synchronise drawing specifications, digital databases and production processes, and rapidly roll out new compatibility solutions. Distributors can obtain updated precision accessories at the earliest opportunity, take the lead in solving end-user compatibility challenges and seize market opportunities.
Leading brands frequently face capacity constraints, regional quota limits and difficulties in cross-region stock transfer. Once brands adjust production capacity or revise regional policies, distributors may suddenly encounter stockouts and delivery delays, directly disrupting operations of end clinics and resulting in customer churn.
Direct manufacturing partnerships feature flexible production scheduling, ready stock reserves and on-demand replenishment, free from brand quotas and regional policy restrictions. Distributors can plan inventory according to their own sales rhythm and flexibly adjust stocking volume, avoiding unsold bulk inventory while ensuring stable supply of hot-selling products, greatly improving supply chain stability and business planning capability.
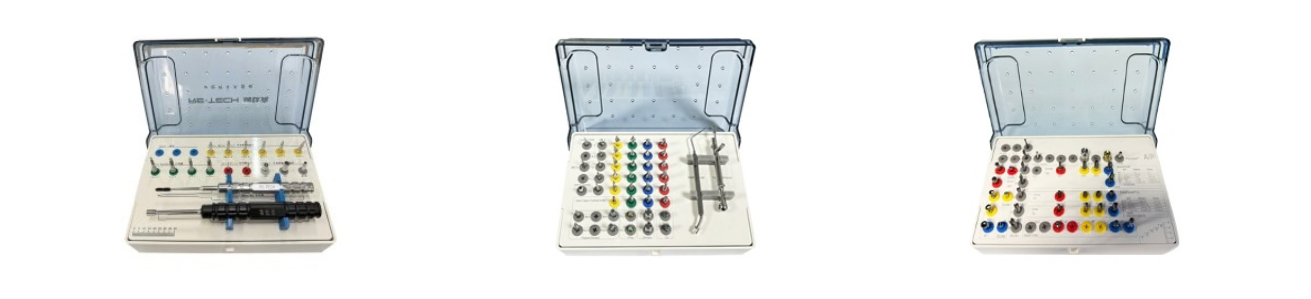
The two cooperation models suit distributors at different development stages, with fundamental differences in profit margin, product authority, iteration speed and inventory planning. A clear comparison helps channels match solutions to their own business needs.
| Comparison Dimension | Traditional Brand Agency Model | Direct Manufacturing Partnership |
| Profit Margin | Compressed by multi-layer markups; transparent profit with low ceiling | Original cost controllable; sufficient and flexibly adjustable profit margin |
| Product Autonomy | Only sell existing product lines; no customisation or modification rights | Support SKU planning, private label customisation, process optimisation and category expansion |
| Product Iteration Speed | Follow brand schedules; delayed iteration and long feedback loops | Direct access to factory R&D; fast adaptation to system version updates |
| Supply Chain Planning | Restricted by brand capacity, quotas and policies; passive inventory management | Flexible production and sufficient ready stock; autonomous control over stocking rhythm |
| Market Competitiveness | Homogenised products; compete only via price cuts | Differentiated products to build long-term customer barriers |
| Cooperation Constraints | Strict annual targets with limited authority | Flexible cooperation with no mandatory quotas; autonomous business control |
Cooperation between distributors and factories is not limited to a single model. Distributors can select solutions based on business scale, customer groups and development plans to fit business demands at different stages.
Suitable for small and medium-sized distributors and start-up channels. Focus on bulk procurement of standard universal accessories and conventional compatible components, with no customisation required, low entry threshold and abundant ready stock. It is mainly used to replace sourcing from traditional agents, directly cut procurement costs, stabilise supply of conventional consumables and rapidly boost baseline profits.
Suitable for distributors with established customer bases who want to build their own brands. Based on the factory’s mature product portfolio, customised exclusive packaging, LOGO, product brochures and outer packaging solutions are available to form a private-brand product line, reduce reliance on public brands and improve customer trust and repurchase loyalty.
Suitable for top-tier distributors and leading regional channels. Combined with unique local market demands, work jointly with factories to optimise product parameters, add rare SKUs, update digital compatibility databases and refine clinical adaptation details, creating regionally exclusive compatible products and building absolute differentiated market advantages.
Beyond improvements in products and supply chains, direct factory partnerships deliver extra value-added support to help distributors expand their business long-term.
Coordinated support for supporting technical documentation: Factories can provide complete sets of documents including product test reports, material certificates, interface compatibility specifications and digital scan libraries. Distributors can deliver these documents directly to clinics and dental laboratories, reducing their own workload of sorting technical files and elevating professional service image.
Customised marketing supporting materials: Beyond products themselves, customised product catalogues, technical manuals and sample display kits can be supplied. When promoting to end customers, complete samples and document packages can greatly improve product demonstration and customer communication efficiency.
Tiered support for orders: Factories provide tiered services ranging from small trial orders to large bulk orders. Distributors can adjust order volume according to market peak and off-peak seasons to match business growth. When developing new customers, small-batch samples can quickly complete clinical verification.
Q1: Are small and medium-sized distributors suitable for direct factory cooperation?
A: Absolutely. There is no need to launch in-depth customisation at the very beginning. You may start with bulk sourcing of standard ready-made products to cut procurement costs and raise profits. After business stabilises, gradually expand into private-label customisation and joint iteration to build your own supply chain system step by step.
Q2: Are complete supporting technical documents available for direct factory cooperation?
A: Reputable professional factories can provide full technical documentation, including material test reports, interface parameter sheets, digital databases and compliance documents required for cross-border sales. Compared with documents relayed layer by layer via brand agents, documents obtained directly from factories are delivered faster and better matched to the products.
Q3: How to quickly screen suitable long-term manufacturing partners for implant components?
A: Focus on verifying three core capabilities: continuous tracking of version updates for major brands, complete batch quality control and test reports, and sound compliance and cross-border documentation systems. Factories with these capabilities can support stable long-term cooperation.
Q4: What is the greatest long-term value of direct factory cooperation?
A: Break free from brand restraints and price monopolies, gain autonomy over products, pricing, product categories and supply chains, transform from “selling others’ products” to “building your own channel brand”, and build sustainable long-term competitiveness.
Q5: Can sample kits for market promotion be obtained when cooperating with factories?
A: Yes. Most manufacturing partners support customisation and supply of sample kits. Distributors can prepare complete restoration component sample sets to demonstrate interface compatibility effects to clinics on-site, which serves as a highly practical tool for acquiring new customers.
The competitive logic of the dental implant component distribution industry has undergone fundamental changes. The extensive model relying on brand traffic and volume sales through agency can no longer cope with the market environment featuring price competition, refined demands and supply chain volatility. Issues including profit bottlenecks, product homogenisation, delayed iteration and supply constraints under the traditional agency model are forcing channels to transform and upgrade.
With core strengths of controllable costs, product autonomy, rapid iteration, stable supply chains and prominent differentiation, the direct manufacturing partnership model has become a core path for global implant distributors to break through growth bottlenecks. By partnering with qualified professional manufacturing factories, distributors can eliminate redundant intermediate links, build their own differentiated product lines, seize market initiative, escape low-price competition and realise the upgrade from simple channel resellers to brand operators.
In the future, the core competitiveness of dental consumable channels will no longer depend on the number of represented brands, but on the capability to control supply chains, create differentiated products and respond rapidly to market changes. Cultivating high-quality factory cooperation resources and building a self-controlled manufacturing supply chain is an inevitable trend for the long-term stable development of all implant distributors.